Mid Term Rental Insurance: 7 Coverage & Liability Essentials for 2026
Mid term rental insurance should protect a furnished rental based on how the property is actually used, including its structure, owner-owned furnishings, liability exposure, and potentially lost rental income after a covered loss. In our experience with MTRs, the biggest mistake is assuming a standard homeowners policy automatically covers repeated 30–90+ day rental activity. Coverage must match the occupancy and business model.
Important: This article provides general educational information, not insurance, legal, or financial advice. Insurance policies, exclusions, endorsements, definitions, and state requirements vary. Hosts should discuss their specific rental arrangement with a licensed insurance professional.
What Makes Good Mid Term Rental Insurance?
Correct rental classification. Your insurer should know that the property is furnished and rented for mid-term stays. Triple-I advises property owners to contact their insurance professional before renting because a standard homeowners policy may not cover losses while the home is rented.
Property and furnishings protection. Good furnished rental insurance should be evaluated for both the building and the owner-owned contents used by tenants, subject to the policy’s covered perils, exclusions, deductibles, and limits.
Adequate liability protection. Mid-term rental liability matters because tenants, visitors, contractors, cleaners, and delivery workers can create bodily-injury and property-damage exposures.
Income protection. Hosts should ask whether loss-of-rental-income coverage applies when a covered loss makes the property uninhabitable. Triple-I says landlord policies commonly provide loss-of-rental-income coverage for a specified period after covered damage.
Clear claims procedures. Hosts should understand deductibles, documentation requirements, exclusions, notice requirements, and the process for reporting a claim before a loss occurs.
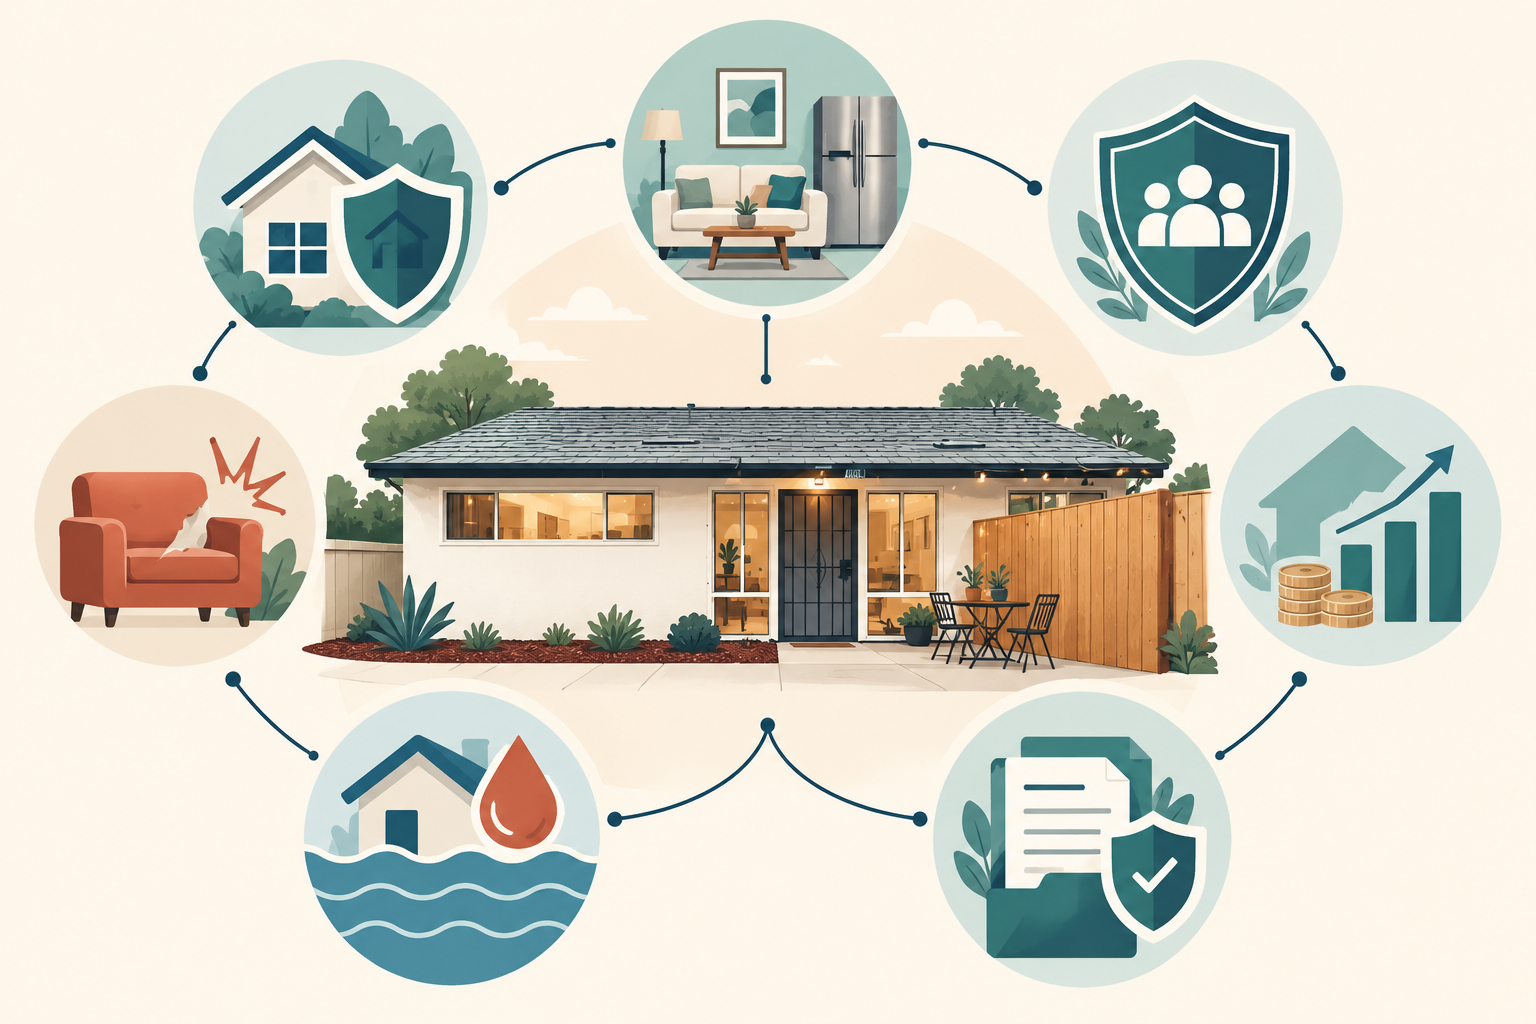
1. Dwelling Coverage for a Mid-Term Rental
Why it matters: The first job of mid term rental insurance is protecting the physical rental property against covered losses.
Coverage detail: Depending on the policy, covered perils may include fire, lightning, wind, hail, and certain other forms of physical damage. Triple-I notes that landlord policies can provide property coverage for damage to the structure from specified covered perils.
Number to check: Review your dwelling limit, deductible, replacement-cost assumptions, and any sublimits that could affect a claim.
Host context: The property should be insured based on its actual rental use. Do not assume a homeowners policy designed for an owner-occupied home provides equivalent protection for a furnished rental business.
This is particularly important when the property was previously a primary residence. Tell the insurer how frequently you rent it, typical lease lengths, whether you occupy it between tenants, and whether it is held specifically as an investment property.
2. Furnished Rental Insurance for Owner-Owned Contents
Why it matters: A furnished MTR contains significantly more owner-owned personal property than a typical unfurnished annual rental.
Coverage detail: Beds, sofas, televisions, desks, dining furniture, appliances, cookware, linens, lamps, and other items can represent thousands of dollars of host investment.
Number to check: Create an inventory with purchase prices, receipts when available, serial numbers for major items, and dated photographs or video.
Host context: Ask whether the policy covers owner-owned contents provided for tenant use and whether settlement is based on replacement cost or another valuation method.
A policy that adequately protects the structure may still leave gaps around furniture and other contents. Therefore, furnished rental insurance should be evaluated specifically for the assets inside the unit.
Do not assume every type of damage is covered. Wear and tear, deterioration, intentional acts, certain water losses, pests, and other causes may be limited or excluded depending on the contract.
3. Mid-Term Rental Liability Coverage
Why it matters: Mid-term rental liability can protect a host when an allegation of bodily injury or property damage creates a covered liability claim.
Coverage detail: A tenant might slip on stairs, a visitor could be injured on the property, or another incident could result in legal expenses or damages.
Number to check: Review the policy’s liability limit and discuss whether it reflects the value of your assets and the property’s risk profile.
Host context: Triple-I explains that landlord policies typically include liability coverage and may cover legal fees and medical expenses when a tenant or guest is injured, subject to the policy.
Liability limits should not be chosen simply because they are the minimum offered. Property configuration, pools, stairs, pets, balconies, fireplaces, and other features can affect risk.
Some owners also discuss umbrella or excess liability coverage with their insurance professional when they need limits above their underlying policy.
4. Tenant Damage, Theft, and Security Deposits
Why it matters: Insurance and security deposits solve different problems, and neither automatically covers every form of tenant damage.
Coverage detail: Hosts should distinguish between accidental covered damage, intentional damage, theft, ordinary wear and tear, and maintenance-related deterioration.
Number to check: Review deductibles before assuming a small furniture or appliance loss is worth filing as an insurance claim.
Host context: A security deposit may address certain tenant obligations under the lease and applicable law, while insurance responds only according to its policy terms.
For example, a broken chair, stained rug, missing television, water leak, and fire can involve completely different coverage questions.
Document the property’s condition before each occupancy. A timestamped photo inventory and signed move-in documentation can make it easier to distinguish pre-existing conditions from new damage.
5. Loss of Rental Income Coverage
Why it matters: Physical damage can stop rental revenue even after the emergency itself is over.
Coverage detail: If a covered fire makes a property uninhabitable for several months, the host can face repair costs and lost rental income simultaneously.
Number to check: Ask how much lost-rent coverage is available and whether the policy imposes a time limit, dollar limit, waiting period, or other conditions.
Host context: Triple-I says most landlord policies provide loss-of-rental-income coverage when covered damage prevents the property from being rented during repair or rebuilding, generally for a specified period.
For an MTR host, documenting achieved rental income is important. Keep leases, booking records, rent payments, and financial statements organized.
A host should also ask how the insurer calculates lost income when monthly rates vary by season or lease length.
6. Flood and Other Common Insurance Gaps
Why it matters: Mid term rental insurance does not necessarily cover every disaster that can damage the property.
Coverage detail: Flood is a major example. The National Flood Insurance Program says flood policies cover direct physical flood damage, while additional living expenses such as temporary housing are excluded.
Number to check: NFIP residential building coverage is available up to $250,000, while residential contents coverage can be available up to $100,000, subject to NFIP rules.
Host context: Flood insurance, earthquake protection, sewer or drain backup, ordinance or law coverage, and other protections may require separate policies or endorsements depending on the property and location.
Hosts should review catastrophe exposure based on the actual property rather than relying on a generic checklist.
For official flood information, see FEMA’s National Flood Insurance Program coverage guidance.
7. Claims and Documentation
Why it matters: Good coverage is more useful when you can document the property, loss, and rental income clearly.
Coverage detail: After a loss, the insurer may need photographs, receipts, repair estimates, leases, income records, inventories, and other evidence depending on the claim.
Number to check: Keep records for every major furniture purchase and maintain a current property inventory rather than trying to reconstruct everything after a loss.
Host context: Triple-I recommends keeping claim documentation and receipts organized and notes that different claims professionals may inspect different aspects of a loss.
Photograph each room, major appliance, television, furniture item, and other valuable host-owned property. Update the inventory when items are replaced.
Also keep copies of leases and rental payment records. If you make a lost-rental-income claim, those records may help establish the property’s rental history.
Mid Term Rental Insurance vs. Homeowners, Landlord, and Renters Insurance
The right policy depends on the property’s actual use. The labels below describe broad insurance categories, not guarantees of coverage.
| Coverage | Homeowners Insurance | Landlord/Rental Dwelling | MTR-Appropriate Host Coverage | Renters Insurance |
|---|---|---|---|---|
| Building | Typically owner-occupied home | Rental dwelling | Should address actual MTR use | No |
| Host furnishings | May be limited by rental use | Depends on policy | Should be specifically reviewed | No |
| Host liability | Personal liability | Landlord liability | Should address MTR exposure | No |
| Tenant belongings | No | No | No | Typically yes for covered losses |
| Tenant liability | No | No | No | Typically included |
| Lost host rental income | Not designed for MTR business | May be available | Should be reviewed | No |
| Tenant temporary housing | No | No | No | ALE may apply after covered loss |
| Business/rental use | Potential restrictions | Designed for rentals | Must match actual use | Protects tenant |
Triple-I specifically warns that standard homeowners insurance typically does not cover commercial short-term rental activities. In March 2026, it said failure to notify an insurer about such activity could contribute to denied claims, reduced liability coverage, higher deductibles, or cancellation. Mid-term stays are not identical to short-term rentals, but the lesson for MTR owners is important: disclose the property’s actual rental use and get coverage designed for it.
Hosts can review Triple-I’s guidance for renting out a home before discussing their specific situation with an insurance professional.
Does Renters Insurance Cover Temporary Housing?
Does renters insurance cover temporary housing? It can when a covered loss makes the renter’s insured home uninhabitable and the policy provides additional living expenses, or ALE.
Triple-I says renters insurance generally includes three main protections: personal possessions, liability, and additional living expenses. ALE can cover costs such as temporary rentals, hotel bills, restaurant meals, and other additional expenses while a covered home is being repaired or rebuilt.
The NAIC similarly explains that ALE may help with temporary housing after a covered disaster, but it generally pays additional expenses above normal living costs rather than every household expense.
This matters to MTR hosts because insurance-displaced renters can become a source of demand for 30–90+ day furnished housing.
However, the tenant’s renters insurance does not replace the host’s mid term rental insurance. The renter’s policy protects the renter’s interests, while the owner needs appropriate coverage for the building, furnishings, rental liability, and income exposure.
Landlord Insurance MTR: Is a Standard Landlord Policy Enough?
A traditional landlord policy may be a better starting point than homeowners insurance for an investment property, but hosts should not assume every landlord policy automatically fits mid-term stays.
Triple-I describes landlord or rental-dwelling policies as appropriate for homes leased to tenants for longer periods, such as six months or a year. It also says these policies generally cost about 25% more than a standard homeowners policy because of the increased protections.
A 30-, 60-, or 90-day furnished rental sits in a different operational pattern from a conventional annual lease. Therefore, when discussing landlord insurance MTR coverage, tell the insurer:
- Typical minimum and maximum stay length
- Number of tenants expected per year
- Whether the property is fully furnished
- Whether utilities are included
- Whether pets are permitted
- Whether the property is an investment or primary residence
- How tenants are screened
- Whether bookings come through platforms or directly
The goal is not to find a policy with “MTR” printed on the label. The goal is to obtain coverage whose terms actually permit and protect the way you operate.
How to Evaluate Mid Term Rental Insurance in 5 Steps
- Describe your rental model accurately. Tell the insurer that you operate a furnished property with typical stays of 30–90+ days. Do not describe it simply as a “rental” if more detail would affect underwriting.
- Inventory the property and furnishings. Estimate the replacement exposure for the structure and document furniture, appliances, electronics, and other owner-owned contents.
- Review liability and exclusions. Ask what happens if a tenant or visitor is injured and identify exclusions relevant to your property.
- Verify income protection. Determine whether covered property damage can trigger loss-of-rental-income coverage, how the benefit is calculated, and how long it lasts.
- Compare the policy, not just the premium. A cheaper policy can be poor value if its exclusions, deductibles, or rental-use restrictions leave important exposures uninsured.
Hosts building their overall rental plan can also use our landlord’s guide to mid-term rentals alongside their insurance review.
What to Do When an MTR Insurance Claim Happens
First, protect people and contact emergency services when necessary. Then report the loss to the insurer according to the policy’s requirements.
Document the damage before cleanup when it is safe to do so. Photograph affected rooms, furniture, appliances, structural damage, and other relevant property.
Next, take reasonable steps required by the policy to prevent additional damage, but avoid permanent repairs until you understand the insurer’s inspection requirements.
Keep receipts for emergency work, temporary repairs, and other claim-related expenses. Triple-I recommends keeping documentation organized throughout the claims process.
Finally, maintain a claim file containing:
- Claim number
- Adjuster contact information
- Photographs and videos
- Property inventory
- Receipts
- Contractor estimates
- Tenant communications
- Lease agreement
- Rental-payment history
- Repair invoices
Good records do not guarantee a claim will be covered, but they can make the loss easier to document.
How to Reduce Mid-Term Rental Liability Risk
Insurance should be one layer of risk management, not the only layer.
Inspect stairs, railings, decks, smoke alarms, carbon-monoxide alarms, electrical systems, locks, walkways, and other safety-related features regularly. Correct known hazards promptly and document maintenance.
Use written leases and clear property rules. Keep records of tenant communications, maintenance requests, repairs, inspections, and contractor work.
Hosts should also screen renters consistently and lawfully. If you are comparing booking and screening approaches, our mid-term rental platform comparison provides additional context.
Most importantly, tell your insurance professional exactly how the property operates. In 2026, Triple-I specifically emphasized the risk of insurance gaps when residential properties are used for rental activity that the existing policy was not designed to cover.
Mid Term Rental Insurance: The Bottom Line
Mid term rental insurance should match the property’s actual 30–90+ day furnished-rental use and address the exposures that matter to the host. Those commonly include the building, owner-owned furnishings, liability, and loss of rental income, subject to policy terms.
Do not assume homeowners insurance, platform protection, a tenant’s renters insurance, or a generic landlord policy automatically fills every gap.
Instead, document your rental model and ask a licensed insurance professional direct questions about occupancy, furnishings, liability, deductibles, exclusions, lost income, flood, and claims.
For hosts, the goal is straightforward: know what is covered before the tenant arrives and before a loss happens.
Ready to market your furnished property to renters seeking flexible 30–90+ day stays? List your property on ministays and build your MTR strategy around transparent leases, responsible screening, and appropriate insurance.
FAQ
What insurance do I need for a mid-term rental?
Mid term rental insurance should be designed or approved for the property’s actual rental activity. Depending on the property and insurer, that may involve landlord or rental-dwelling coverage plus appropriate protection for furnishings, liability, and lost rental income. Tell the insurer that typical tenants stay 30–90+ days and confirm the arrangement in writing.
Does homeowners insurance cover a mid-term rental?
Do not assume it does. Triple-I advises homeowners to contact their insurer before renting because standard homeowners coverage may not protect losses occurring while a property is rented. The answer depends on the policy, frequency of rental activity, occupancy, and insurer, so disclose the exact MTR arrangement before accepting tenants.
Does renters insurance cover temporary housing after a covered loss?
Yes, renters insurance can provide additional living expenses when a covered disaster makes the insured residence uninhabitable. Triple-I says ALE can cover temporary rentals, hotels, restaurant meals, and other additional costs, subject to policy terms and limits. It does not mean every temporary housing expense will automatically be reimbursed.
Does mid-term rental insurance cover tenant damage?
It depends on the policy and cause of damage. Accidental covered damage, intentional damage, theft, ordinary wear and tear, and deterioration can be treated differently. Hosts should ask specifically how tenant-caused damage is handled, what exclusions apply, and what deductible would apply before relying on insurance instead of other risk-management measures.
Does landlord insurance cover furniture in an MTR?
Some landlord policies provide protection for certain owner-owned personal property used to service or maintain a rental, but coverage varies. Triple-I notes landlord policies can cover certain property left on-site for tenant use. Furnished MTR hosts should specifically inventory beds, sofas, televisions, appliances, desks, and other contents and confirm how their policy treats them.
Does mid-term rental insurance cover lost rental income?
Some landlord or rental-property policies can provide loss-of-rental-income protection when covered property damage prevents the home from being rented. Triple-I says this coverage is commonly provided for a specified period. Hosts should confirm the limit, covered causes, benefit period, and documentation required to establish their normal rental income.
Does flood insurance cover temporary housing for renters?
NFIP flood insurance does not cover additional living expenses such as temporary housing. NFIP guidance lists ALE and financial losses from loss of use among items not covered by building or contents coverage. Renters and hosts should therefore avoid assuming an NFIP policy will pay for temporary accommodation after a flood.